Event report
CFO committee meeting on minimum top-up tax: "Pillar Two Readiness and the Next Wave of Tax Disputes"
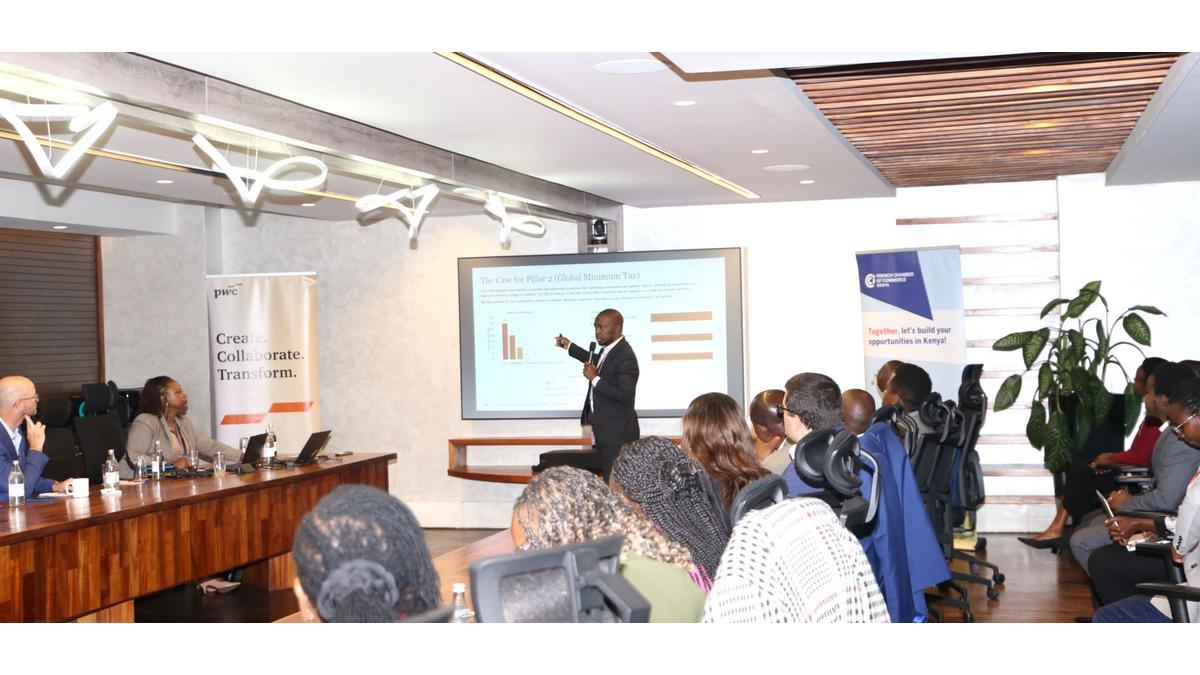
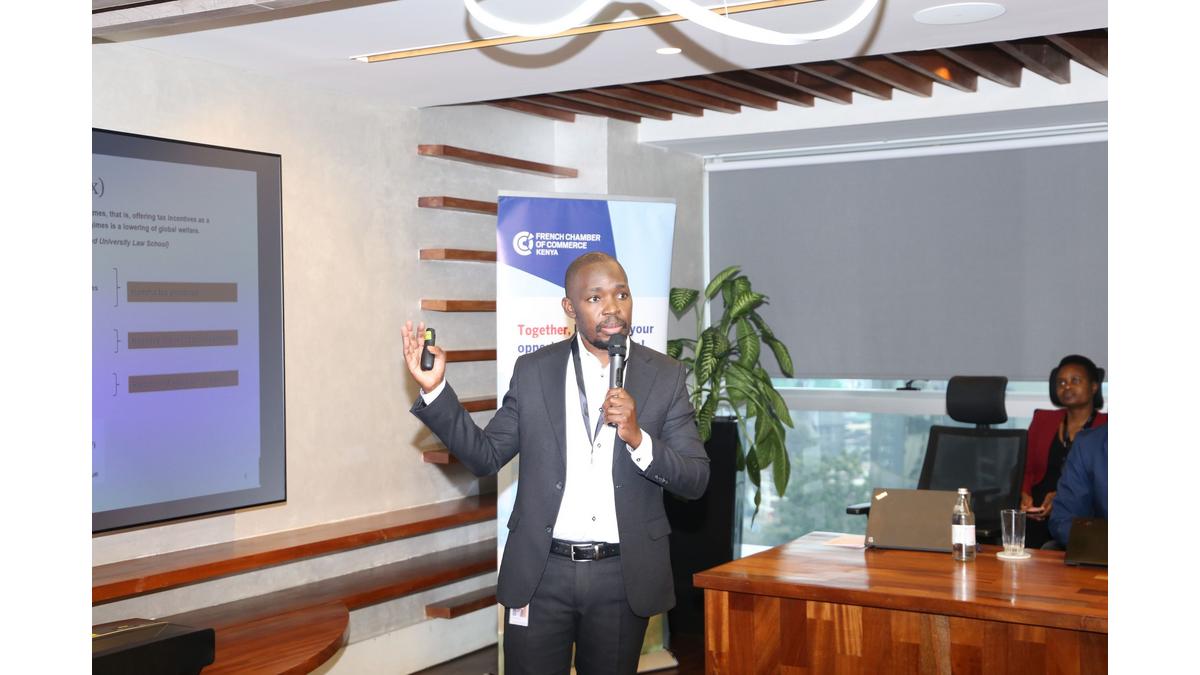
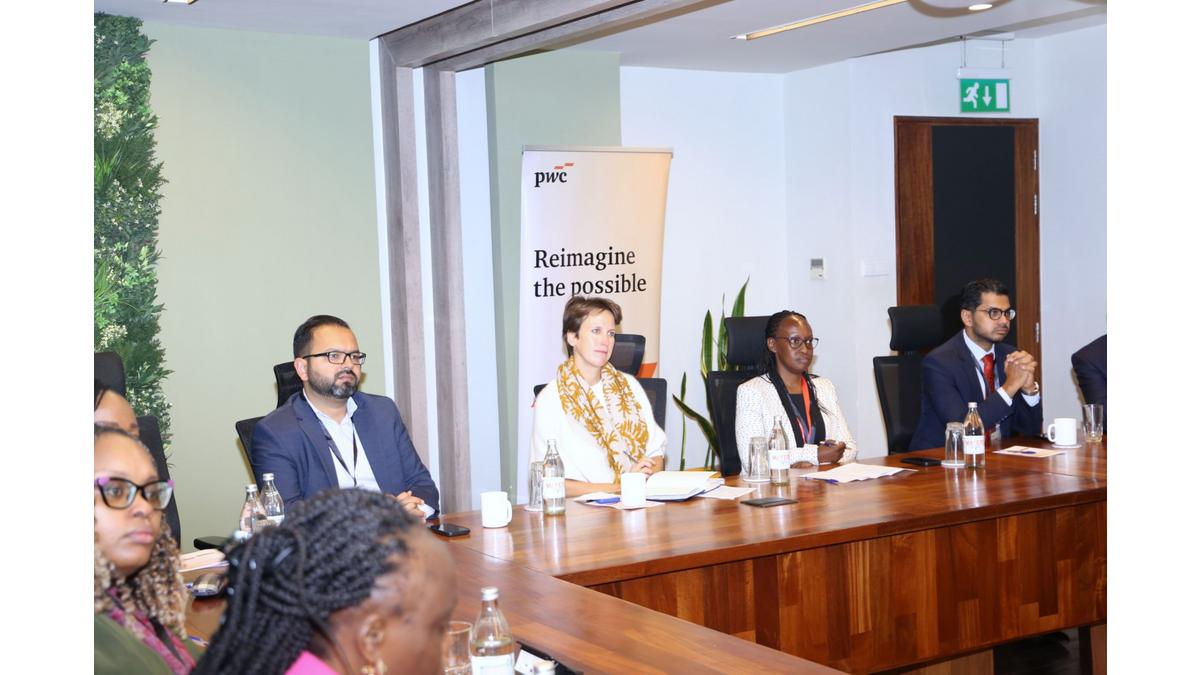
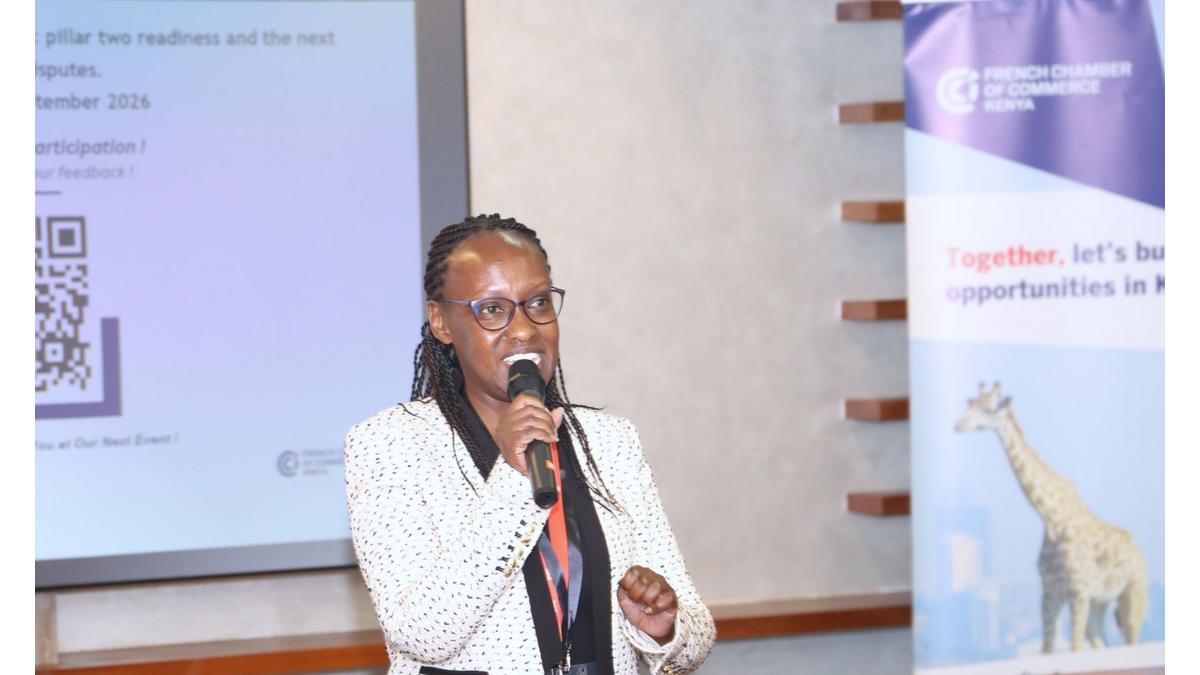
Finance leaders gathered at PwC Towers on Tuesday, 22nd September 2026, as the FCCK Kenya hosted an exclusive CFO committee session alongside our member, PwC Kenya.
Led by PwC tax experts Joseph Khaemba, Edwine Mango, and Janet Lavuna, this roundtable brought together senior finance executives to unpack "Minimum Top-Up Tax: Pillar Two Readiness and the Next Wave of Tax Disputes". The discussion provided practical strategies for multinational enterprises in Kenya navigating OECD’s Pillar Two GloBE framework, assessing exposure, and building dispute readiness.
Key takeaways from the session included:
- Kenya's pillar two adoption: Kenya has introduced the Qualified Domestic Minimum Top-Up Tax (QDMTT) under Section 12G of the Income Tax Act to collect top-up taxes locally for MNE groups exceeding the EUR 750M global revenue threshold.
- Impact on local tax incentives: preferential regimes, including Special Economic Zones (SEZs) and Export Processing Zones (EPZs), alongside accelerated capital allowances can lower an entity’s Effective Tax Rate (ETR) below 15%, triggering top-up tax exposure.
- Compliance and timeline mismatches: with draft regulations still awaiting finalization, businesses face operational challenges where payment deadlines precede domestic return filing dates.
- Enhanced KRA enforcement: recent statutory changes give the KRA commissioner broader powers to issue assessments using third-party data, deploy pre-populated returns, and strictly enforce anti-avoidance measures.
- Strengthening tax governance: developing robust internal tax governance, backed by reliable data, strong controls, clear escalation paths, and alternative dispute mechanisms (MAP/ADR), is essential to mitigating audit risks.
A sincere thank you to PwC Kenya for collaborating with us on this session, and to all the CFOs and finance leaders who contributed to this insightful exchange!